Pakistan tax
Documents Required for Income Tax Return in Pakistan: A Checklist
IRIS asks for figures, not folders. Here are the papers behind them for tax year 2026: which the law requires, which just back you up, and who gives you each.
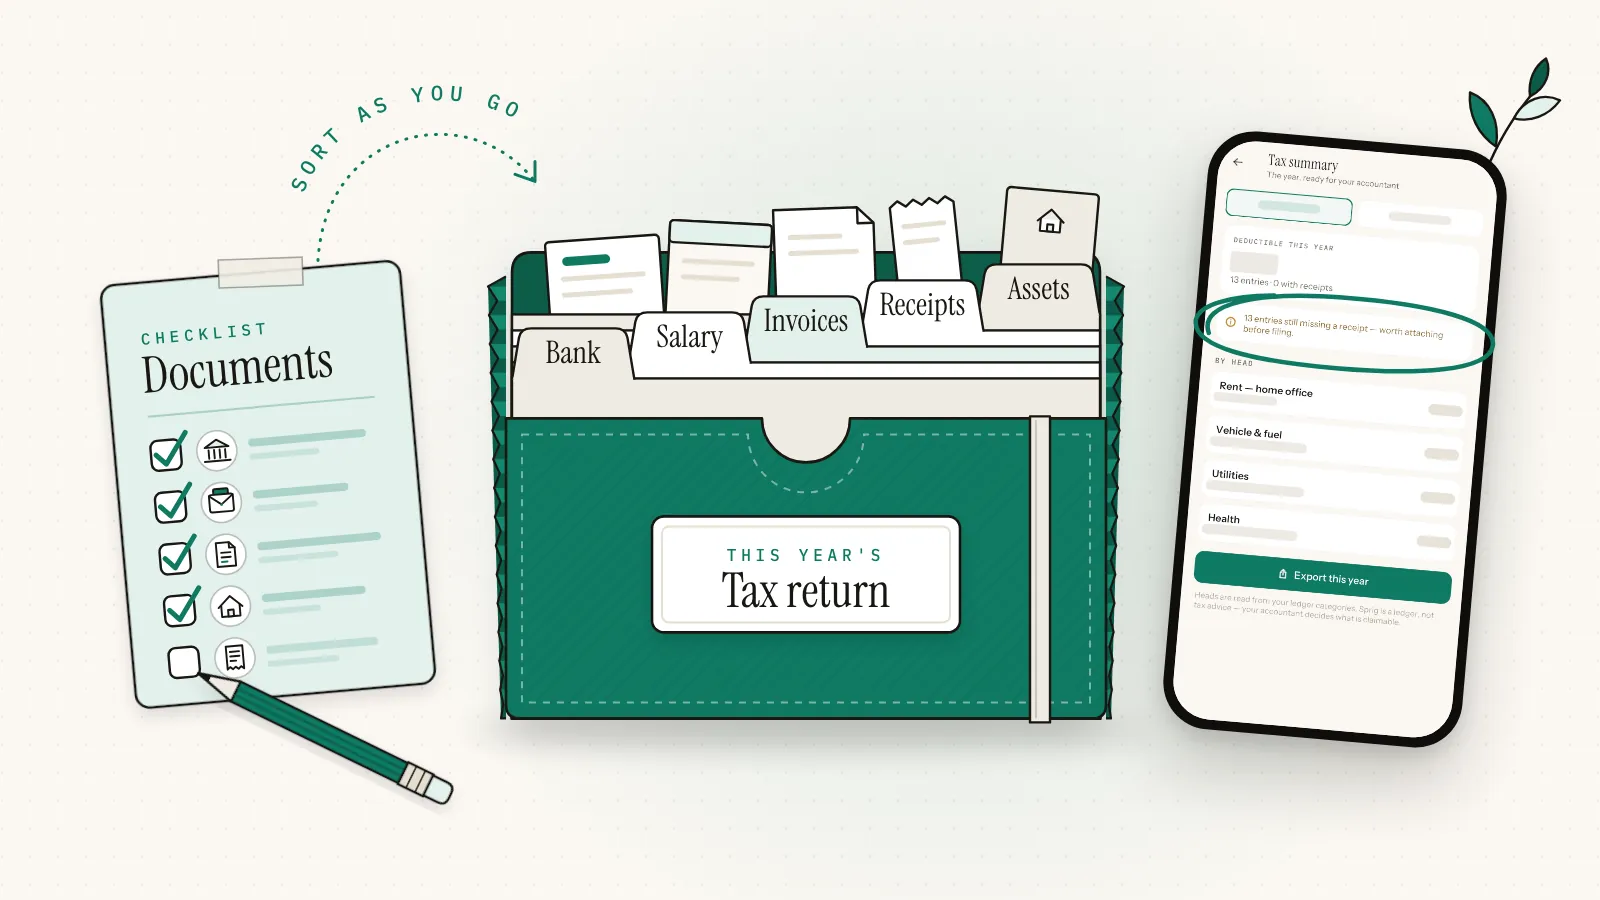
Every figure in your IRIS return should trace back to a paper you can show if FBR asks. This checklist covers tax year 2026 (1 July 2025 to 30 June 2026), due by 15 October 2026.
| Fact | Rule | Law |
|---|---|---|
| Tax year 2026 | 1 July 2025 to 30 June 2026 | Income Tax Ordinance, 2001, s.74 |
| Return due | 30 September by law; extended to 15 October 2026 for tax year 2026 | s.118(3); FBR Circular No. 3 of 2026-27 |
| Sent with the return | Proof of tax paid, the wealth statement, and the foreign income and assets statement if it applies | s.114(2)(d)–(f) |
| Tax certificates | Whoever deducts or collects tax from you must give you a certificate and CPR copies; your return attaches the CPRs | s.164(1)–(2) |
| Missing proof | A business expense can be disallowed or reduced if, without reasonable cause, you can't produce a receipt or other record | s.174(2) |
| Cash donations | Count for the credit only if paid by crossed cheque | s.61(4) |
| Keeping records | Six years after the tax year ends | s.174(3) |
Not tax advice. Rules change every June with the Finance Act, so confirm anything unusual with FBR or a registered tax practitioner.
What documents are required for an income tax return in Pakistan?
By law, a resident individual's return must come with a wealth statement, proof of any tax paid with it, and CPR copies behind each certificate of tax deducted. Income Tax Rules 29 to 31 add records to keep for each kind of income, such as a salary certificate or rent receipts. Bank statements and bills back up the rest.
The whole income tax return checklist fits on one screen. "Required" means the Ordinance or rules 29 to 31 of the Income Tax Rules, 2002 ask for it; backup papers support your figures if FBR asks. Salaried? See our guide to the tax return for salaried persons.
| You are | Required by law or the Rules | Useful backup | Who gives it to you |
|---|---|---|---|
| Everyone | CNIC (your NTN) and IRIS login; CPR copies behind each certificate of tax deducted (s.164(2)); proof of tax paid with the return (s.114(2)(d)); a wealth statement, if you're a resident individual (s.116) | Every bank statement; last year's wealth statement, if any; asset and loan papers; household bills | You, your banks, anyone who deducted tax |
| Salaried | Salary certificate showing pay and tax deducted (rule 31(1)) | Payslips | Employer |
| Freelancer | Your bank's certificate of tax deducted under s.154A, with CPRs | Invoices and platform payout statements; PRCs; PSEB certificate, for the 0.25% rate | Clients, platforms, your bank, PSEB |
| Business owner | Books under rules 29 and 30 (below); customers' s.153 certificates, with CPRs | Statements for the business account you declared (s.114A); advance-tax CPRs (s.147) | Your own books, customers, your bank |
| Landlord | Tenancy agreement, if signed, and rent receipts (rule 31(2)); the tenant's s.155 certificate, with CPRs, if tax was deducted | Bank statements showing rent received | You and your tenant |
| Property or vehicle owner | After selling property at a gain, proof of cost, other costs and sale price (rule 31(3)); CPRs for tax collected at transfer (s.236K buying, s.236C selling), registration (s.231B) or with token tax (s.234) | Deed or transfer papers, registration book and purchase invoice, to declare the asset at cost | Registrar or housing authority, dealer, excise office |
| Anyone with money or assets abroad | Foreign income and assets statement, if you're a resident individual with at least USD 10,000 of foreign income or USD 100,000 of foreign assets (s.116A) | Foreign bank statements, property papers and income records | Foreign banks and agents |
- CPR
- Computerized Payment Receipt: proof that tax reached the government, whoever paid it.
- PRC
- Proceeds Realization Certificate: a bank's proof that money from abroad arrived in rupees.
Do you upload documents to IRIS?
IRIS mainly asks for figures, so most papers stay with you, ready to show if FBR asks. The law makes two exceptions: copies of the CPRs behind your certificates of tax deducted go with the return (s.164(2)), as does evidence of any tax paid with it (s.114(2)(d)). The return's Attachment tab has upload slots for final accounts.
Start here
FBR's tax year 2026 return forms (SRO 1495(I)/2026) open on a Summary of Economic Transactions, which lists the tax FBR has on record as withheld from you and has a Download Detailed Data button. FBR calls it indicative and says correct reporting is "primarily your own responsibility", so treat it as a list of certificates to collect.
- Download the withholding summary. Each line is a certificate or CPR to collect.
- Chase missing certificates. Whoever deducted tax owes you one (s.164(1)).
- Total your own records of income, costs and household spending for the tax year.
- Open last year's wealth statement. Its closing net assets become this year's Net Assets Previous Year.
If a certificate and the summary disagree, ask the deductor to fix it before you claim. Finance Act 2026 added a penalty equal to any withholding credit claimed beyond what was verifiably deducted and deposited (s.182, table entry 36).
Which bank documents do you need?
Get a statement for every account you held during the tax year, closed ones included, plus each bank's certificate of profit paid and tax deducted. The 30 June balances go into your wealth statement. If money came from abroad, also get the bank's proceeds realization certificates (PRCs), or its yearly statement of them.
A bank statement for your tax return proves balances and shows what came in and went out, though not why. Rule 31(4)(c) of the Income Tax Rules accepts a certificate or a bank statement as evidence of bank profit and the tax deducted from it, and rule 31(4)(h) wants loans and gifts shown arriving by crossed cheque or through a bank. Banks issue an electronic PRC as soon as foreign funds are credited, and an electronic statement of PRCs for the year (State Bank of Pakistan, 2022).
Keep PRCs even if you never freelance. Up to Rs 5 million a year of foreign remittances, received through banking channels (exchange companies and money transfer operators count) and encashed in rupees by a scheduled bank, falls outside the unexplained-income rule if you produce the bank's certificate (s.111(4)). Bank profit is covered in our guide to withholding tax in Pakistan.
What the table doesn't tell you
Freelancers
Pair each invoice or payout with its PRC: one shows the work, the other that the money arrived. Your bank deducts tax on realization (s.154A) at 0.25% for PSEB-registered IT and IT-enabled services exporters (tax years 2024 to 2029), or 1% otherwise. For example, on Rs 500,000 that's Rs 1,250 instead of Rs 5,000, so keep the PSEB certificate in the folder. Keep a copy of each filed return too: PSEB asks for the previous year's return when you renew. Rupee payments from Pakistani clients fall outside s.154A, so keep the rule 30 business records below for that work. More in freelancer tax in Pakistan.
Sole proprietors and shopkeepers
Rule 29 asks for proper books, including assets and liabilities; rule 30 sets the minimum for anyone but a company. With business income up to Rs 500,000, or a new business: numbered, dated cash memos or invoices, a daily record of sales, receipts, purchases and expenses, and vouchers. Above that, and for wholesalers, distributors, dealers and commission agents, add a ledger or annual summary, payee names and addresses on vouchers over Rs 10,000, and a quarterly stock inventory if you trade goods. Professionals such as doctors and lawyers use numbered client slips and an appointment diary (rule 30(3)). See business tax for sole proprietors.
Landlords, property and vehicle owners
If your tenant is a company, a government office, a private school, a clinic, or anyone paying Rs 1.5 million or more a year in rent, it must deduct tax under section 155 and give you a certificate. The property and vehicle taxes in the table are adjustable under the Ordinance, with some exceptions, so their receipts count toward your tax. Owning a vehicle above 1000cc, or certain property, can itself oblige you to file (s.114(1)(b)); see how to file your income tax return in Pakistan.
How do you prove household expenses for the wealth statement?
No one issues a certificate for household spending, so the proof is your own: rent receipts, utility bills, school fee vouchers, medical bills, and bank and card statements. Total them for 1 July to 30 June. IRIS won't accept a wealth statement that doesn't reconcile, so build the total from real bills rather than working backward from the gap.
Section 116(1) covers spending by you, your spouse, minor children and other dependents. If the spending you declare is below a reasonable amount, section 111(3) lets the Commissioner add the difference to your income, and section 111(1) does the same for spending whose source you can't explain. Records are your answer to both.
FBR's instructions to its 2019 return forms (SRO 1160(I)/2019) say to declare assets at cost, including ancillary expenses, so keep purchase papers for property, vehicles, gold, shares and funds, and loan statements as of 30 June. The tax year 2026 reconciliation has separate lines for foreign remittances, inheritance and gifts, and each needs a paper trail. Then fill the wealth statement so it reconciles.
What proof do tax credits need?
You need proof that you paid within the tax year, to an eligible recipient, in the way the law requires: donation receipts (with the crossed cheque for cash), a pension fund statement, fee vouchers with the school's NTN or name, evidence of Zakat paid, and a lender's statement of home-loan profit.
| Claim | Proof to keep | Who gives it to you |
|---|---|---|
| Donations (s.61) | Receipt from an eligible institution; a crossed cheque for any cash donation (s.61(4)) | The institution, your bank |
| Voluntary Pension System (s.63) | Statement of your contributions to an approved pension fund | Pension fund manager |
| Tuition fees (s.60D) | Fee vouchers; the school's NTN or name (s.60D(4)) | The school |
| Zakat (s.60) | Evidence of Zakat paid under the Zakat and Ushr Ordinance, 1980, such as Zakat your bank deducted | Your bank, or wherever you paid it |
| Home-loan profit (s.63A) | Lender's statement of profit paid; loan and property papers | Your bank or other lender |
Caps and formulas are in our guide to the legal ways to save tax in Pakistan.
How long should you keep tax documents in Pakistan?
Keep them for six years after the end of the tax year they relate to (s.174(3)), so tax year 2026 papers stay until at least 30 June 2032. Keep them longer while any proceeding is pending, and with no time limit for records of assets or spending abroad, or foreign-source income, that section 111 can reach.
Electronic copies are allowed under rule 32(1) of the Income Tax Rules if you keep them safe and intact. Compare the rules in how long to keep business records, and set up a receipt system that sticks.
Turning a year of entries into a filing pack with Sprig
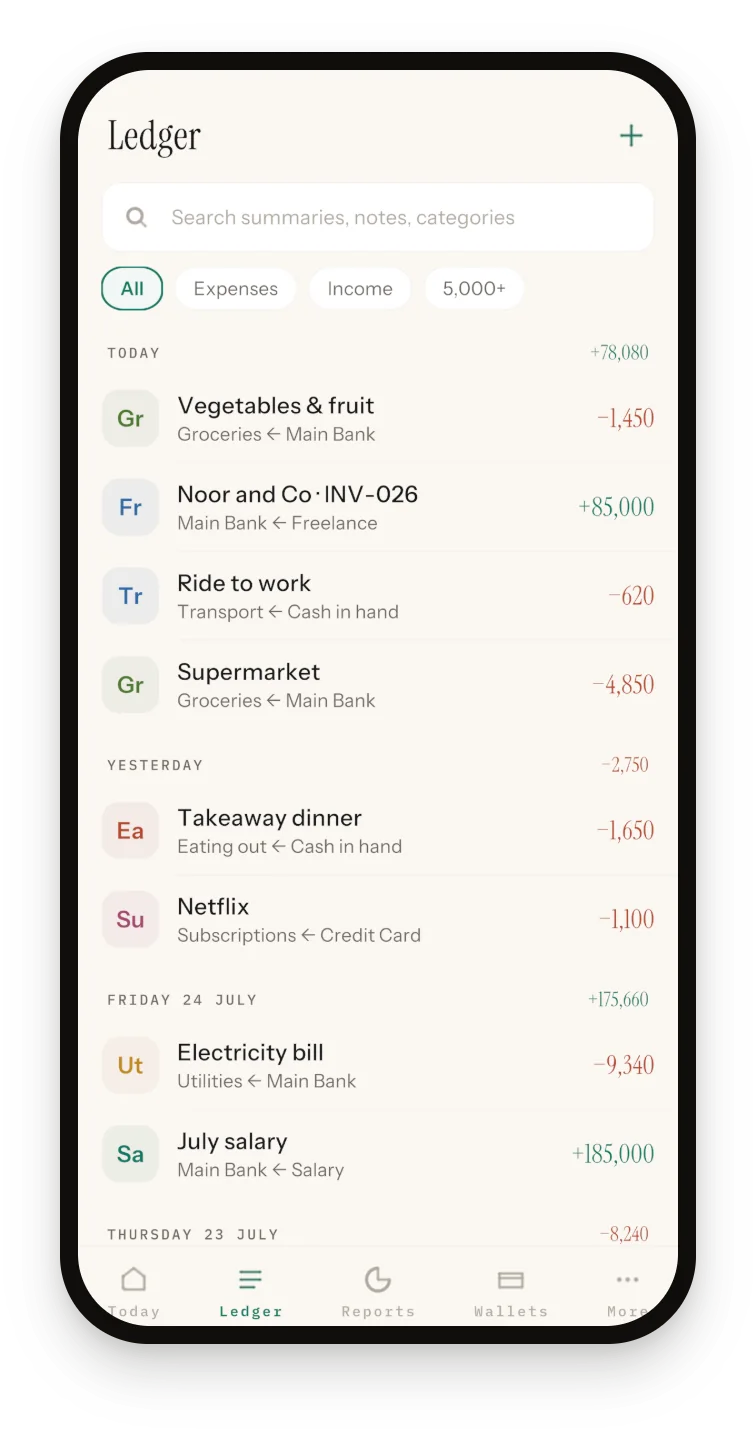
Sprig is a private, offline double-entry bookkeeping app for iPhone and Android, made by Secundum Reality. Its tax summary follows Pakistan's July–June tax year. It has no account, no bank link and no cloud, and it doesn't calculate tax or file returns. Its FY 2025–26 is what FBR calls tax year 2026.
How Sprig helps
It can't replace a certificate, but it produces the records only you can make.
- One CSV per book. Export → Last FY in the Personal book, then in Side business. In October 2026, Last FY is tax year 2026.
- The household total. Reports → Range, 1 July 2025 to 30 June 2026, in the Personal book. Transfers between your own wallets never count as spending.
- Missing receipts. The tax summary counts expense entries without one. Photos can't be attached to entries you've already typed: a receipt saved with type, category and amount becomes a new entry, dated with the photo's date. If you photograph an expense you typed, delete the typed entry, or it counts twice.
- Your own labels. Categories such as Tax deducted or Zakat show in Reports and the CSV, though not in the tax summary.
Know the limits. Receipt photos aren't in the CSV or the backup, so keep originals of certificates and deeds. Keep tax figures in PKR wallets, since totals don't convert currencies. Typed entries are dated the day you save them; rebuild last year by importing a CSV with Date, Category, Account and Amount columns. See how the offline bookkeeping app works.
Sprig for iPhone and Android
Keep your books in four taps.
Private, offline double-entry bookkeeping. No account, no bank login, no cloud. Free to start with 50 entries.
Frequently asked questions
What documents do I need to register on IRIS for the first time?
FBR's online registration page lists a SIM registered against your own CNIC, a personal email address, and a certificate that you hold a personal bank account in your own name. Business owners add proof of tenancy or ownership of the premises and a paid utility bill under three months old. The page is undated, so check IRIS itself. Your CNIC is then your NTN (s.181(4)).
What if I lost a certificate of tax deducted or a receipt?
Ask whoever deducted the tax for a duplicate: section 164(1) of the Income Tax Ordinance requires them to give you a certificate with copies of the CPR. Meanwhile, the Summary of Economic Transactions in your IRIS return shows the withholding FBR has on record. For a lost receipt, ask the seller for a copy and keep the bank or card statement that shows the payment.
Is a bank statement enough proof of income for a tax return in Pakistan?
Not on its own. A statement proves money arrived, not what it was for or whether tax was deducted. Pair each credit with the paper that explains it: a salary certificate, an invoice and PRC for a foreign client, a tenancy agreement for rent. For bank profit, though, rule 31(4)(c) of the Income Tax Rules does accept a statement as evidence.
Does Sprig give me anything I can submit to FBR?
No. Sprig is a ledger on your phone: it doesn't connect to IRIS, file anything or calculate tax. It gives you a CSV of this or last July–June year for each book, category totals in Reports, and a count of expenses still missing a receipt, for filling in the return yourself or briefing a tax practitioner.
Sources and further reading
- FBR: Income Tax Ordinance, 2001, amended up to 30 June 2026 (ss.61, 74, 111, 114, 116, 116A, 155, 164, 174, 182)
- FBR Circular No. 3 of 2026-27: tax year 2026 return date extended to 15 October 2026
- FBR: Income Tax Rules, 2002, amended up to 15 September 2026 (rules 29 to 32)
- FBR: SRO 1495(I)/2026, tax year 2026 electronic return forms
- PSEB (Tech Destination): freelancer registration
- State Bank of Pakistan: banks to issue proceeds realization certificates electronically (6 August 2022)
Published 3 October 2026. Feature details were checked against Sprig 1.1 for iPhone and Android. This article is general information, not tax or legal advice; rules differ by country, so confirm anything you file with your accountant or tax authority.