Pakistan tax
Income Tax Refund in Pakistan: How to Claim It From FBR
Overpaid tax can come back, but only on the law's timetable. Here's when you're owed a refund, how the section 170 application works on IRIS, and what holds payment up.
An income tax refund in Pakistan usually has to be claimed. If more tax was taken from you than you owe, the Income Tax Ordinance, 2001 gives you three years to apply, gives FBR 60 days to decide, and adds compensation when payment is late.
| Rule | What the law says | Law |
|---|---|---|
| Time limit | 3 years from the later of the assessment order or the date the tax was paid | s.170(2)(c) |
| Decision | A written order within 60 days, after you've had a chance to be heard | s.170(4) |
| Set-off | The excess first clears other tax you owe | s.170(3) |
| No application | From tax year 2021, FBR may refund system-verified credit on its own | s.170A |
| Late payment | KIBOR + 0.5% a year once 3 months pass after the refund order | s.171 |
| Late filers | No refund while off the Active Taxpayer List | s.182A(1)(c) |
Not tax advice; rules change every June with the Finance Act; confirm with FBR or a registered tax practitioner.
When are you owed an income tax refund in Pakistan?
You're owed an income tax refund in Pakistan when the tax credited to you for a year, meaning adjustable tax deducted or collected plus advance tax you paid, is more than the tax your return shows as chargeable. Sections 147(10) and 168(5) say that excess "shall be refunded to the taxpayer" under section 170.
IRIS works this out when you click Calculate in the return. Common causes:
- One-off transactions. Adjustable tax on buying property (s.236K), selling one owned since an earlier tax year (s.236C) or registering a car (s.231B) can exceed the tax on a modest income.
- Advance tax. Quarterly installments (s.147) follow last year's assessed tax. If your income fell, section 147(10) sends the excess to section 170.
- Credits. A donation (s.61) or VPS pension contribution (s.63) claimed in your return can cut your tax below what your employer deducted. See filing as a salaried person and the legal ways to save tax in Pakistan.
Example
For example, your tax year 2026 return shows tax chargeable of Rs 180,000. Your employer deducted Rs 165,000 and Rs 30,000 was collected when you registered a car, so Rs 15,000 is refundable. Tax deducted from savings profit stays out of the sum: bank profit up to Rs 5 million is final tax (ss.7B, 8).
Which tax can't be refunded?
Final tax generally can't be refunded. Tax on dividends, on bank profit up to Rs 5 million, on prize bonds and, when its conditions are met, on export proceeds under section 154A settles the tax on that income; only an over-deduction comes back. Minimum tax is a floor: it stays even when your normal tax works out lower.
| Type | Examples | Refundable? | Law |
|---|---|---|---|
| Adjustable | Salary (s.149), rent received (s.155), buying property (s.236K), selling property bought in an earlier tax year (s.236C), car registration and token tax (s.231B, s.234), card payments abroad (s.236Y) | Yes, any excess | s.168(5) |
| Advance tax | Quarterly installments you pay | Yes, any excess | s.147(10) |
| Minimum | A resident individual's receipts for goods, services and contracts (s.153); bank profit above Rs 5 million (s.151); electricity bills up to Rs 360,000 a year (s.235); selling property bought in the same tax year (s.236C) | No: it's the least you pay on that income | s.153(3); s.151(3); s.235(4); s.236C(2) |
| Final | Dividends; bank profit up to Rs 5 million; prize bonds; s.154A export proceeds (see freelancer tax in Pakistan) | No credit, no refund | s.8; s.168(3); s.169 |
Over-deduction is the exception: section 169 bars a refund of final tax "unless the tax so collected or deducted is in excess of the amount for which the taxpayer is chargeable". Tax taken at the higher rate for people not on the Active Taxpayer List becomes adjustable if you file before FBR makes a provisional assessment, or within 45 days of receiving one; for a final tax, only the excess over the normal rate counts (s.169(4); Tenth Schedule, rule 4). See withholding tax in Pakistan for the rates.
How do you claim a tax refund from FBR?
To claim a tax refund from FBR, file your return electronically, then submit a separate refund application under section 170 on IRIS. FBR's 2023 guides list it under Refund as "170 (Application for refund of tax paid in excess)". Give the tax year, income, tax chargeable and tax paid, attach evidence such as withholding certificates, and submit.
- File the return. Rule 73(2E) of the Income Tax Rules requires both the return and the refund application to be filed electronically. For tax year 2026, FBR extended the deadline to 15 October 2026 (Circular No. 3 of 2026-27); here's how to file your income tax return in Pakistan.
- Check FBR's record. The tax year 2026 return opens on a Summary of Economic Transactions listing tax withheld from you, with a Download Detailed Data button (SRO 1495(I)/2026). Claim only what was deposited: since 1 July 2026, over-claiming credit costs a penalty equal to the excess (s.182, entry 36).
- Add your IBAN. FBR asks taxpayers to add their complete IBAN to the bank details in their IRIS profile so refunds can be paid electronically.
- Open the application. Choose Refund on the top menu. In FBR's 2023 guides, you then pick "170 (Application for refund of tax paid in excess)" and select the tax period.
- Fill it in. The prescribed form (Part VI of the Rules' First Schedule) asks for total income, tax chargeable, tax paid and the refund claimed. Add evidence of the tax paid if it isn't already with your return: withholding certificates and payment receipts (CPRs), which withholding agents must give you (s.164).
- Submit and answer questions. In FBR's 2023 help-center guide, the officer can send a "Clarification Required" request with a due date, and you reply from the application's Assignment tab. You're entitled to be heard before the decision (s.170(4)).
Check the labels
Only the Refund item on the top menu is confirmed for tax year 2026, on the IRIS screens printed in SRO 1495(I)/2026. The rest of the path, including the Assignment tab, comes from FBR guides dated 2023 (its Iris FAQs and a help-center article of 9 February 2023), so labels on today's IRIS 2.0 may differ.
How long does FBR take to refund, and what if it's late?
The Commissioner must send a written decision within 60 days of your application, after giving you a chance to be heard (s.170(4)); if none comes, you can appeal. If an approved refund isn't paid within three months of the refund order, FBR owes compensation for the delayed refund at KIBOR + 0.5% a year until it pays.
- Assessment order
- A complete return counts as one (s.120), so the three-year clock never starts before the day you file.
- Refund order
- The decision on your application. For compensation, the refund falls due on this date, not when you filed (s.171(2)).
- KIBOR
- The Karachi Inter Bank Offered Rate on the first day of each quarter of the financial year (s.2(30AB)).
| Step | Legal limit | Example | Law |
|---|---|---|---|
| Apply | 3 years | Return filed 10 Oct 2026; application made 1 Nov 2026 | s.170(2)(c) |
| Written order | 60 days | Due by 31 Dec 2026; say it is made on 20 Dec 2026 | s.170(4) |
| No order in time | Appeal | To the Commissioner (Appeals) | s.170(5); s.127 |
| Compensation | 3 months | If still unpaid on 20 Mar 2027, KIBOR + 0.5% a year runs until payment | s.171 |
Under the Income Tax Rules (r.210IC), the refund order goes to FBR's Centralized Income Tax Refund Office, which has the State Bank of Pakistan credit your account. Section 170A lets FBR refund system-verified credit without an application, but it's a power, not a promise, so apply anyway. We found no official figure for typical payout times.
A tax year 2026 return filed in October 2026 keeps the window open until at least October 2029. As of October 2026, FBR's refund help page still says two years, the rule before the Finance Act 2016.
Can late filers get a tax refund?
Not while you're off the Active Taxpayer List (ATL). Under section 182A, anyone who misses the due date, or an extended date, is left off the ATL for that year unless they pay a surcharge, gets no refund while off it and earns no compensation for that time. For tax year 2026, FBR's extended due date is 15 October 2026.
The law doesn't cancel the refund: section 182A(1)(c) withholds it only "during the period the person is not included in the active taxpayers' list". To get on the list, a late filer files and pays the section 182A surcharge. The Finance Act 2026 raised it from Rs 1,000 to Rs 25,000 for individuals, but FBR hasn't confirmed which applies to late tax year 2026 returns, so check what IRIS asks for. Individuals may instead give a six-month undertaking not to acquire property, but the Income Tax Rules amended to 15 September 2026 don't yet prescribe its form. See what late filing costs.
What delays a tax refund?
A refund can stall on anything FBR must check or settle first: credit it can't match to tax actually deposited, missing evidence, unanswered questions, tax owed for another year, time off the ATL or bank details that bounce. A claim FBR believes is inadmissible earns no compensation until its investigation ends (s.171).
- Unverified credit. Credit is checked against tax "verifiably deducted and deposited by the withholding agent", as confirmed by FBR's system (s.182, entry 36). If a certificate doesn't match the IRIS withholding summary, take it up with the deductor before you claim.
- Missing evidence. The application must carry the documents the form calls for (Rules r.71(3)).
- Unanswered questions. In FBR's 2023 guide, clarification requests come with a due date.
- Old demands. Unpaid tax for other years is deducted first (s.170(3)).
- The ATL. Check your status by texting ATL, a space and your 13-digit CNIC to 9966.
- Bank details. A payment the State Bank returns goes back to the Commissioner for correction (r.210IC(5)).
Keep certificates and CPRs for at least six years after the tax year ends, and longer while any proceeding, such as an appeal, is pending (s.174(3)). More on how long to keep records.
Tracking tax deducted, and the refund, in Sprig
Sprig is a private, offline double-entry bookkeeping app for iPhone and Android, made by Secundum Reality. Its tax summary follows Pakistan's July–June tax year. It has no account, no bank link and no cloud, and it doesn't calculate tax or file returns. It can't tell you whether you're owed a refund, but it can keep the record a claim rests on.
How Sprig helps
Log deductions as they happen, and the year's total is ready when you file.
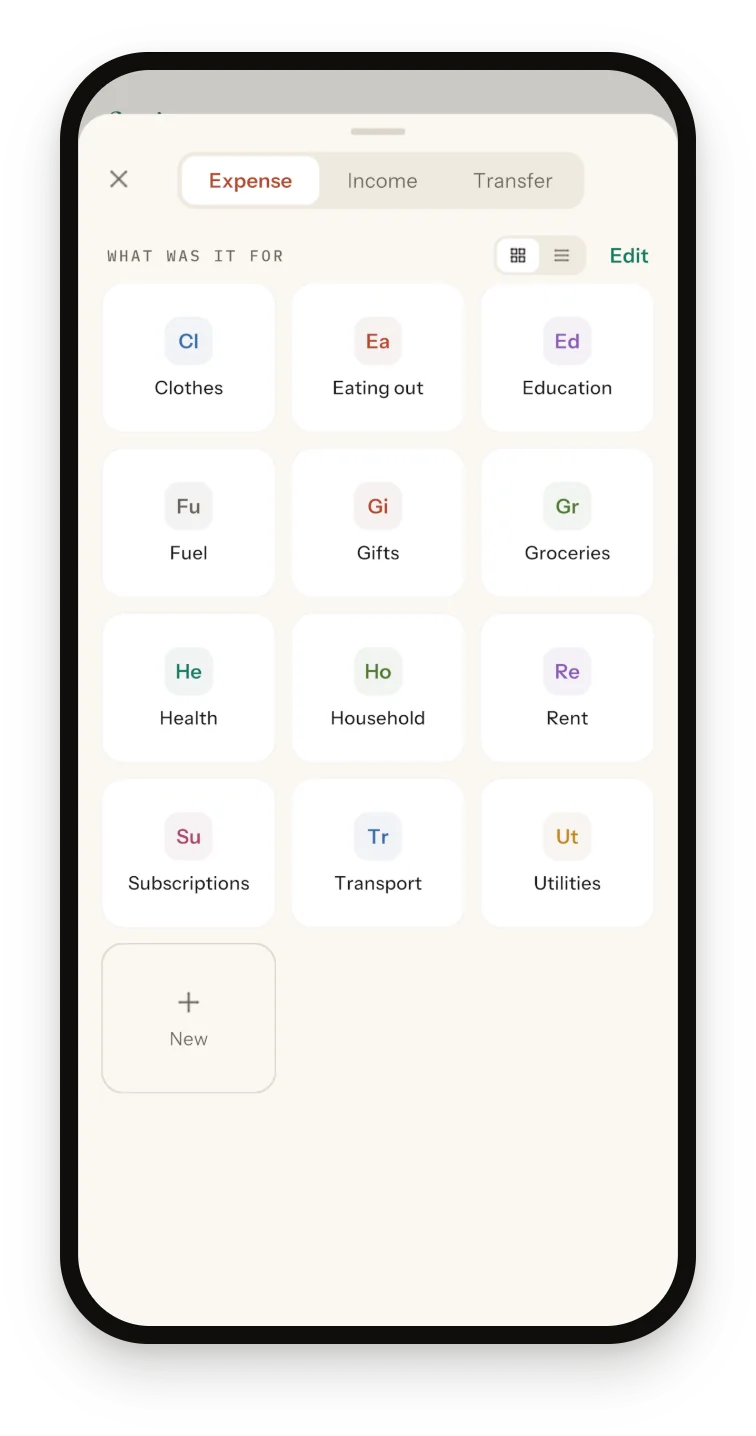
- A Tax deducted category. Add it with the + New tile in the entry sheet, with summaries such as Salary or Car registration. On payday, log gross pay as Salary income and the tax as Tax deducted from the same wallet, so the wallet matches what the bank received.
- The year's total. In Reports, a custom range of 1 July 2025 to 30 June 2026 (tax year 2026) shows the Tax deducted total, which expands per summary, ready to compare with the withholding summary IRIS shows.
- A CSV. In October 2026, Export's Last FY is tax year 2026, for the book that's open.
- The refund. Log it under the built-in Refunds income category, with a note such as "TY2026 refund".
What Sprig won't do
- Work out a refund. Sprig has no tax rates or FBR rules, and its tax summary's five heads are its own groupings, not deductions or credits under the Ordinance.
- Talk to FBR. It doesn't connect to IRIS, see FBR's data or track your application or ATL status.
- Backdate a typed entry. Entries take the date you save them; for earlier deductions, import a CSV with Date, Category, Account and Amount columns.
- Back up certificate photos. Photos in Receipts stay on the phone, outside the backup and the CSV, so keep the originals.
Sprig for iPhone and Android
Keep your books in four taps.
Private, offline double-entry bookkeeping. No account, no bank login, no cloud. Free to start with 50 entries.
Frequently asked questions
How many years back can I claim an income tax refund?
Three years. Section 170(2)(c) of the Income Tax Ordinance, 2001 allows an application within three years of the later of the assessment order for that tax year and the date the tax was paid. FBR's refund help page still says two years, but the Finance Act 2016 changed the law to three.
Can I get back the 0.25% tax deducted from my freelance income?
Usually not. When the conditions in section 154A(2) are met, including filing your return, the bank's deduction from export proceeds is final tax: no credit, and no refund unless more was deducted than you're chargeable for (sections 168(3) and 169). You can opt out of final taxation each year when you file (section 154A(3)), but whether that helps depends on your figures, so ask a registered tax practitioner.
Will FBR deduct tax I owe from my refund?
Yes. Under section 170(3), the Commissioner first applies an overpayment to any other tax you owe under the Income Tax Ordinance, then to other outstanding tax liabilities, and refunds only what's left. FBR's 2023 help-center guide shows the officer's refund screen deducting earlier years' demand before it allows the refund.
Does FBR pay interest if my refund is late?
It pays compensation, not interest. If a refund isn't paid within three months of falling due (for an application, the date of the refund order), section 171 adds KIBOR plus 0.5% a year from the end of those three months until payment. Nothing is added for time off the Active Taxpayer List, or while a doubtful claim is being investigated.
Does Sprig calculate my income tax refund?
No. Sprig is a bookkeeping app: it doesn't compute tax, credits or refunds, and it doesn't connect to IRIS. It keeps the records instead: a custom Tax deducted category totaled for July to June in Reports, a CSV of the last financial year, and the refund logged under the built-in Refunds income category when it arrives.
Sources and further reading
- FBR: Income Tax Ordinance, 2001, amended up to 30 June 2026 (sections 168 to 171 and 182A)
- FBR: Income Tax Rules, 2002, amended up to 15 September 2026 (rules 71, 73 and 210IA to 210IC; refund form in Part VI of the First Schedule)
- FBR: Iris FAQs (2023), including how to file an application for refund
- FBR: Income tax refund, adding your bank IBAN to the IRIS profile
- FBR: SRO 1495(I)/2026, tax year 2026 electronic return forms
- FBR Circular No. 3 of 2026-27: return deadline for tax year 2026 extended to 15 October 2026
Published 3 October 2026. Feature details were checked against Sprig 1.1 for iPhone and Android. This article is general information, not tax or legal advice; rules differ by country, so confirm anything you file with your accountant or tax authority.